
Budget App — PocketGuard
- Rating
- 4.5
- Downloads
- 100.00K
- Content Rating
- Everyone
Budget App — PocketGuard - Screenshots
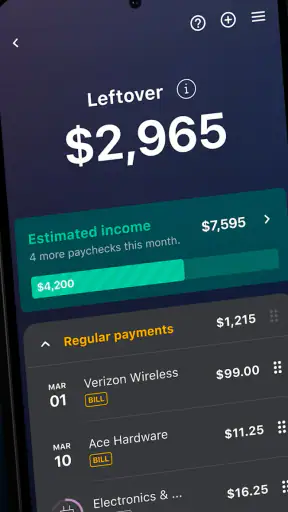
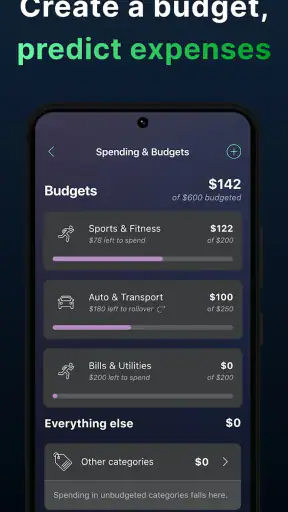
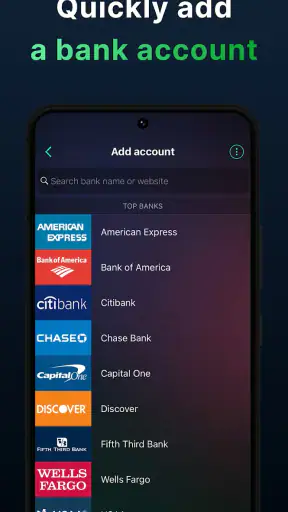
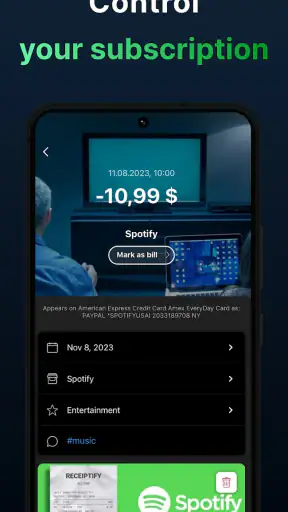
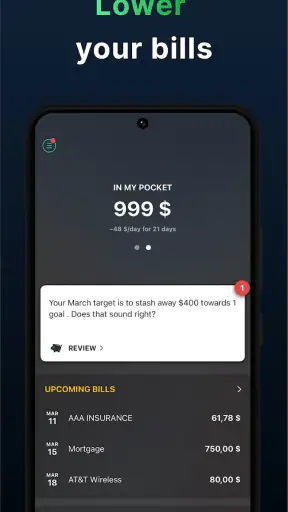
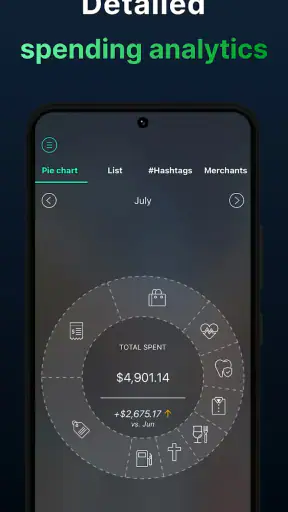
Pros
- Connects bank accounts to track spending automatically.
- Clear budget overview makes finances easy to understand.
- Useful alerts can help prevent overspending.
- Supports recurring bills and subscription tracking.
- Available on both Android and iOS devices.
Cons
- Many advanced features require a paid PocketGuard Plus plan.
- Bank connection support may vary by country and institution.
- Automatic categorization can occasionally misclassify transactions.
- Some users may dislike sharing financial data with a third party.
- Limited customization compared with more detailed budgeting tools.
Budget App — PocketGuard - Description
- App Name
- Budget App — PocketGuard
- Package Name
- com.pocketguard.android.app
- Developer
- PocketGuard, Inc.
- Category
- Finance
- Last Updated
- Mar 16, 2016
- Version
- 5.19.3
Managing money usually fails for a simple reason: the information is scattered, and checking it feels like another chore. PocketGuard approaches that problem as a personal finance app for watching spending, organizing income, controlling expenses, and making room for savings. I found its appeal strongest when I treated it as a quick daily checkpoint rather than a complete financial command center.
That distinction matters. A budgeting tool can look useful during its first few days, when every screen feels fresh, but lasting value depends on whether it still helps after the initial setup. In my experience, this app has a reasonable chance of staying useful for people who want a clear view of everyday cash flow. It is less convincing for someone who wants highly detailed accounting, extensive investment tracking, or a budgeting system that demands precise manual control over every transaction.
What PocketGuard feels like during the first week
The first week is when the app makes its best impression. Instead of asking me to build a complicated spreadsheet from scratch, it gives the budgeting process a more immediate shape: look at income, notice spending, identify expenses, and decide what can safely remain available. That sequence matches the questions most people actually ask before payday: What have I already spent? What bills are coming? How much can I use without creating a problem later?
I like this practical focus because it avoids one common mistake in finance apps: confusing more detail with more understanding. A long list of categories can be technically impressive but still leave the user unsure what to do next. PocketGuard is more approachable when I need a fast reality check, especially after several small purchases have made my balance look healthier than it really is.
A realistic use case is a busy week in which I buy lunch, pay for transport, renew a subscription, and pick up household items without making any single large purchase. None of those transactions feels alarming by itself. Together, however, they can quietly reduce the money available for bills or savings. Opening the app at the end of the day gives me a reason to look at the combined effect rather than relying on memory.
The most useful habit is checking before spending, not only after spending. If I look at PocketGuard before ordering something optional, the decision becomes less emotional. I can compare the purchase with upcoming obligations and my current saving intention. That is a small workflow change, but it is more valuable than simply admiring a neatly organized transaction history.
The app is free to install and is suitable for everyone from an age-rating perspective. Optional purchases range from under a dollar to well over a hundred dollars per item, so I would pay attention to the purchase screen before committing to anything beyond the basic experience. The free entry point makes experimentation easy, but it also means users should decide early whether the available tools are enough for their routine.
Where the setup helps and where it asks for patience
Any finance app depends on accurate information, and PocketGuard is no exception. The initial experience is only useful if I take time to review the way income and expenses are represented. I would not blindly trust the first overview. I would check recurring obligations, look for transactions that need attention, and make sure the picture reflects my real household situation rather than a rough approximation.
This is an important trade-off. Automation can reduce repetitive work, but it can also make a budget feel finished before it has been properly reviewed. My advice is to use the first week as an audit period. Notice which expenses are easy to understand, which ones require correction, and whether the app’s presentation matches the way you personally think about money.
For a single person with a fairly stable income, that process may be quick. For a household with shared spending, irregular earnings, cash purchases, or several financial priorities, it can take more attention. PocketGuard can still be useful, but the app will not remove the need for judgment. A clean overview is not the same thing as a perfect plan.
Turning the first look into an actual routine
I would use three short check-ins during the opening week. The first would be a broad review of income and fixed expenses. The second would focus on recent discretionary spending, especially purchases that are easy to underestimate. The third would happen before the next major payment or bill, when the information can influence a real decision.
This approach is better than opening the app repeatedly without a purpose. It also reveals whether PocketGuard fits naturally into daily life. If the app helps me answer a question in less time than opening a spreadsheet or calculating figures manually, it earns a place in my routine. If every visit turns into a correction session, the initial convenience may not last.
Why the value can continue from month to month
The strongest long-term role for PocketGuard is as a spending-awareness tool. It can help me notice patterns that are difficult to see in isolation: frequent small purchases, recurring expenses that no longer feel worthwhile, or a gap between what I intend to save and what actually remains. The value is not in checking a number once. It is in making the same useful decision repeatedly.
That makes the app more suitable for people who need a gentle financial boundary than for people who already maintain a detailed budget with discipline. Someone who regularly loses track of variable spending may benefit from a central view. Someone who already categorizes every transaction, forecasts several months ahead, and enjoys building custom formulas may find the experience less satisfying than a spreadsheet or a more specialized planning service.
One of the less obvious benefits is that the app can support a “pause before purchase” habit. Rather than assigning a monthly target and forgetting it, I can treat the available-spending view as a prompt to ask whether today’s choice affects tomorrow’s obligations. This is particularly useful for irregular discretionary costs, because they often cause more trouble through repetition than through size.
Another practical workflow is to pair a weekly review with a monthly reset. During the week, I would only look for surprises and avoid trying to redesign the entire budget. At the end of the month, I would examine which categories repeatedly exceeded expectations and adjust my behavior before the next cycle. This keeps the app from becoming an all-day financial project.
Saving money also becomes more realistic when it is connected to actual expenses. A savings intention that ignores annual renewals, seasonal costs, or occasional household purchases is easy to break. PocketGuard is most helpful when I use its spending picture to make that intention more conservative and believable. I would rather set a target I can maintain than create an ambitious number that forces me to abandon the plan after one expensive week.
How it compares with familiar alternatives
Compared with a spreadsheet, PocketGuard is more convenient for quick checks and less flexible for users who want to design every calculation themselves. A spreadsheet can represent unusual income arrangements, shared accounts, debt schedules, and custom categories exactly as I choose. The cost is maintenance: I have to enter, organize, and interpret the information myself. PocketGuard’s appeal is reducing that friction, provided its presentation fits my needs.
Compared with a simple banking app, PocketGuard has a more deliberate budgeting purpose. A bank app is excellent for confirming balances and individual transactions, but it may not encourage the same broader question about what remains available after expenses. PocketGuard is useful when I want the balance to be interpreted within a spending plan rather than viewed alone.
Compared with an envelope-style cash system, the app is less physical and less restrictive. Envelopes create a strong behavioral limit because money is visibly assigned before it is spent. PocketGuard offers more convenience, but convenience can also make it easier to ignore a warning. Users who need firm, almost automatic spending barriers may prefer a method with stronger separation between categories.
Finally, compared with a highly specialized finance platform, PocketGuard feels more focused on everyday budgeting than on becoming a complete financial record. That focus is a strength for beginners and busy users. It is a limitation for anyone expecting deep analysis across investments, taxes, complex debt strategies, or detailed household accounting. I would choose it for clarity and routine awareness, not for every possible financial task.
The maintenance burden after the novelty disappears
The app’s lasting usefulness depends on a modest amount of maintenance. I would not describe budgeting as completely automatic, because financial information still needs occasional attention. New recurring expenses, changed income, unusual purchases, and personal priorities can all make an old budget less relevant. The danger is not that PocketGuard becomes difficult overnight; it is that I stop checking whether its picture still matches reality.
My preferred routine would be a short weekly review and a more careful monthly review. The weekly visit is for catching surprises. The monthly visit is for deciding whether the spending plan needs adjustment. This is enough structure to preserve the app’s purpose without turning money management into a daily obsession.
There is also a useful distinction between maintenance and micromanagement. I would not edit every minor detail immediately unless it changes a decision. If a small transaction does not affect my available spending or savings plan, correcting it may not be worth the time. On the other hand, an overlooked recurring bill deserves attention because it can distort the entire month.
That judgment is where experienced use matters. A beginner may assume every figure must be perfect before the app can help. I think the better standard is decision-making accuracy: does the information help me avoid overspending, prepare for obligations, and save consistently? Perfection is valuable only when it improves those outcomes.
The developer, PocketGuard, Inc., has kept the app in active use across multiple platform generations. It was released in the middle of the last decade, and the current Android version is 5.19.3 with Android 8.0 or later required. For me, that makes compatibility worth checking before installation on an older device, particularly if the phone is no longer receiving regular system updates.
What creates fatigue over time
The first source of fatigue is repetition without a visible payoff. If I open the app every day merely to confirm that spending is still happening, the routine will quickly feel pointless. The app needs to lead to an action: delaying a purchase, changing a subscription, moving money toward savings, or preparing for a bill. Without that link, even a clear interface becomes background noise.
The second source is correction work. Financial tools can lose their appeal when I spend more time fixing classifications or reviewing unexpected entries than learning from them. I would give PocketGuard a fair trial, but I would also be honest about the time it asks from me. If the overview repeatedly conflicts with my records, a manual spreadsheet may actually be less frustrating because I control the structure from the beginning.
The third is emotional fatigue. Budgeting can make every purchase feel like a small moral test, especially for people who are already anxious about money. I would use PocketGuard as a guide, not as a source of guilt. A realistic plan should leave room for ordinary enjoyment. If the app encourages constant self-criticism rather than better choices, the user may abandon it even when the information is useful.
There is also a privacy and trust consideration whenever a person uses a finance app. I would read the app’s current permissions and policy information before connecting anything sensitive, and I would use the strongest device security available. That is not a criticism unique to PocketGuard; it is simply sensible behavior for any tool involved in personal finances.
Who will get the most from it
I would recommend PocketGuard to someone whose main problem is losing sight of everyday spending. It is a good candidate for a person starting a first budget, rebuilding a routine after repeated overspending, or trying to turn a vague savings goal into a monthly decision. The average rating is around four and a half stars from roughly three thousand ratings, and the app has passed one hundred thousand installs, which suggests that its straightforward budgeting role resonates with a substantial group of users.
I would be more cautious about recommending it to a person with highly irregular income, complicated shared finances, or a need for detailed long-range forecasting. It may still provide a useful overview, but it should not be treated as the only financial record. Likewise, users who dislike linking financial information to third-party tools or who want complete manual control may feel more comfortable with a local spreadsheet or a bank’s own budgeting features.
It is also not the right choice for someone expecting a full investment dashboard or professional accounting workflow. PocketGuard’s strength is helping ordinary spending decisions become more visible. Asking it to replace every other financial tool would create disappointment that comes from choosing the wrong category of solution.
My long-term verdict
After the novelty fades, PocketGuard earns its space when I use it as a lightweight checkpoint rather than a financial command center. Its recurring value comes from turning scattered spending into a question I can answer before the month gets away from me. That is a meaningful benefit, especially for people who know they should budget but struggle to maintain a spreadsheet.
Its weakness is equally clear: no budgeting app can make a plan self-maintaining. I still need to review unusual expenses, question recurring commitments, and decide what matters most. If the app’s overview requires too many corrections or if I need advanced customization, another option may serve me better. The free starting point makes it reasonable to test that fit without a large initial commitment, while optional purchases mean I would keep an eye on what I actually need.
My final recommendation is positive but specific. Try it if your goal is to build a repeatable spending check, especially before discretionary purchases and at the start of a new month. Give it enough time to pass the first-week excitement, then judge it by one question: does it help you make better decisions with less effort? If the answer remains yes, PocketGuard can become a practical companion for everyday budgeting. If you want exhaustive control, complex forecasting, or a complete financial archive, I would choose a more specialized alternative instead.
FAQ
What is PocketGuard, and who is it best suited for?
PocketGuard is a personal finance and budgeting app designed to help you monitor spending, organize bills, and understand how much money is available for everyday use. After connecting your financial accounts, the app presents a simplified overview of income, recurring expenses, and spending habits. It is especially useful for people who want an automatic budgeting experience rather than building detailed spreadsheets manually.
Is PocketGuard safe to use with my bank accounts?
PocketGuard uses account connections to retrieve financial information and display it inside the app, so security is an important consideration before signing up. The service generally relies on established financial-data connection providers and does not need your bank password for ordinary budgeting activity after setup. However, users should still review the app’s privacy policy, enable available security protections, and only connect accounts they are comfortable managing through a third-party service.
Does PocketGuard automatically create a budget for me?
One of PocketGuard’s main conveniences is that it can organize your financial information automatically after you connect supported accounts. The app considers income, bills, subscriptions, savings goals, and spending to estimate what remains available. This can save considerable setup time, although the results depend on accurate account data and properly categorized transactions. Users should review categories and recurring payments because automatic budgeting may occasionally require manual corrections.
Is PocketGuard free, or does it require a subscription?
PocketGuard offers access to some budgeting features without payment, but advanced tools may be reserved for a premium plan, commonly known as PocketGuard Plus. Premium availability, pricing, and included features can vary by platform, location, and current subscription terms. Before downloading or starting a trial, check the purchase screen carefully for renewal details, billing frequency, and cancellation requirements so you understand the cost after any introductory period.
Can PocketGuard help me cancel subscriptions and save money?
PocketGuard can help identify recurring expenses by showing bills, subscriptions, and regular payments in one place, making it easier to notice services you no longer use. Depending on the version and region, certain features may also provide assistance with managing or canceling subscriptions. It does not replace reviewing bank statements yourself, however. Check each recurring charge carefully, confirm cancellation directly with the provider, and monitor future transactions to ensure billing has stopped.


